Money Basics
The principles behind interest, prices, purchasing power, and cash flow.
Money Basics, in depth.
 Analysis
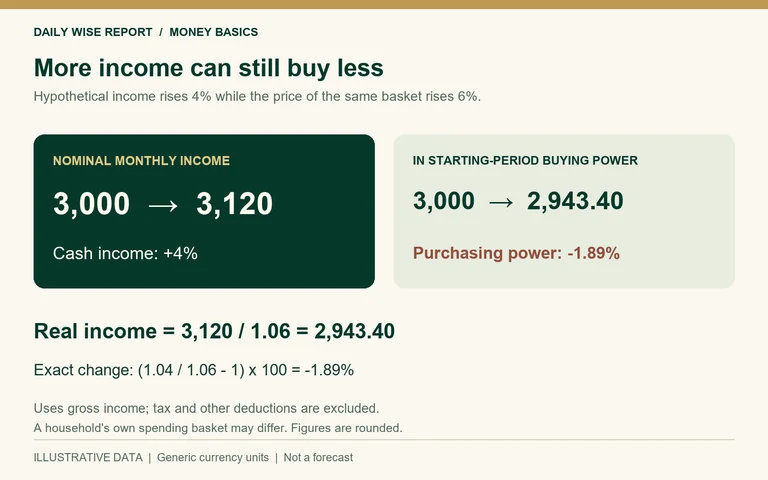
When a Pay Raise Buys Less: Understanding Real Income
A higher income figure can coexist with lower purchasing power. The result depends on prices, deductions and what is being compared.
Read full article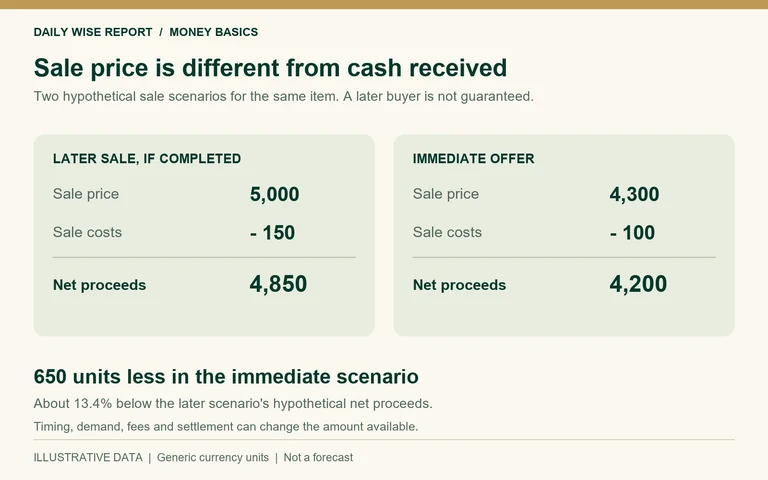 Analysis
Liquidity vs Value: Why an Asset May Not Pay an Immediate Bill
An estimated value is not the same as cash available today. Sale timing, transaction costs and uncertainty can separate the two.
Read full article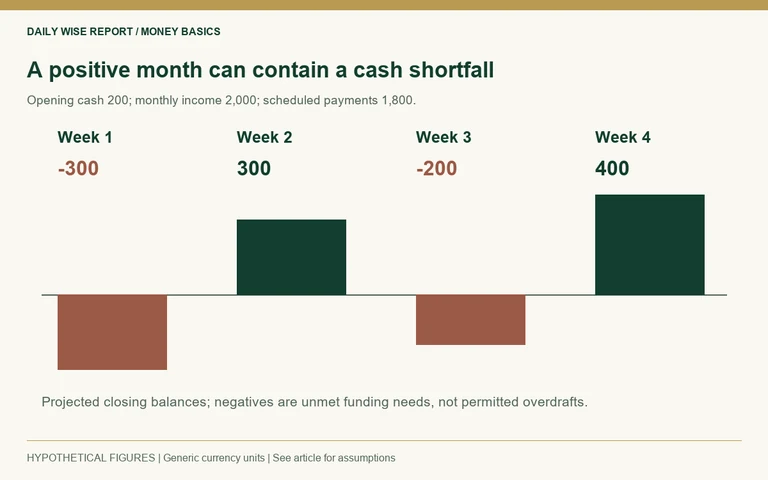 Analysis
Cash Flow Is Not Net Worth: Why Timing Can Create a Shortfall
A household can own valuable assets and still lack cash when a bill is due. The distinction is about time as well as totals.
Read full article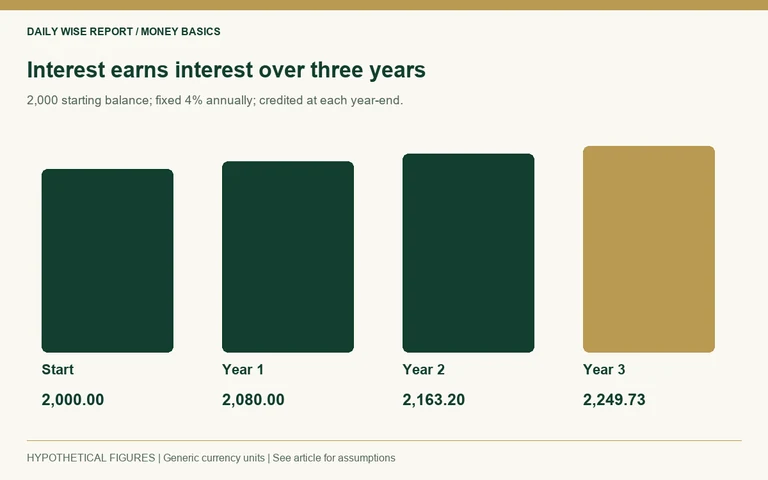 Analysis
How Compound Interest Works—and What the Headline Rate Leaves Out
A growing balance is only part of the story. Timing, fees, and changing prices shape what that growth means.
Read full article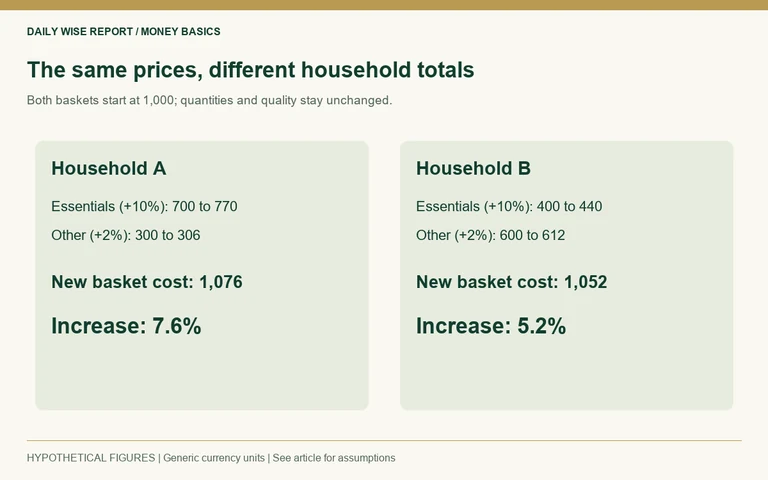 Analysis
Why Inflation Feels Different from One Household to Another
One published rate summarizes many prices. It cannot describe every household’s basket, income, or housing situation.
Read full article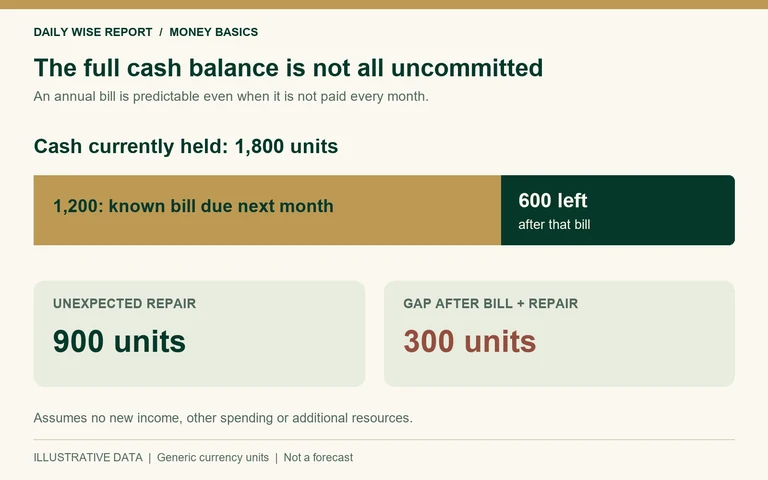 Analysis
Emergency Funds and Predictable Bills Solve Different Problems
An annual bill can arrive infrequently without being unexpected. Separating timing from uncertainty changes the analysis.
Read full article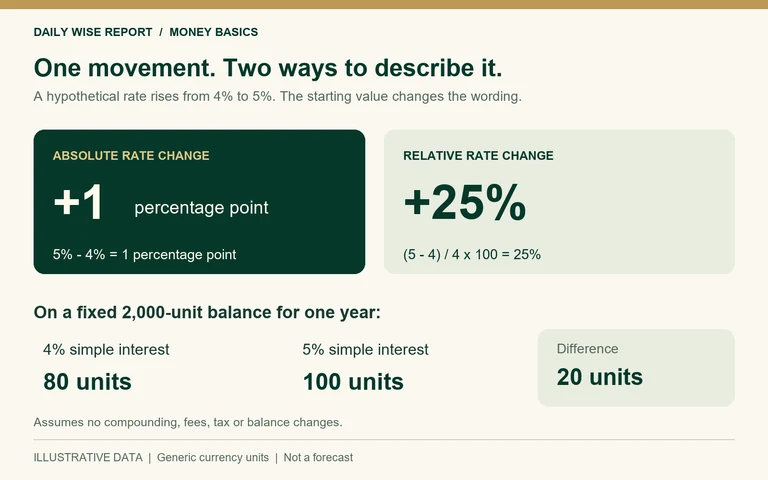 Analysis
Percent vs Percentage Points: Why the Same Change Can Sound Very Different
A rate can rise by one percentage point and by 25% at the same time. The denominator explains the difference.
Read full article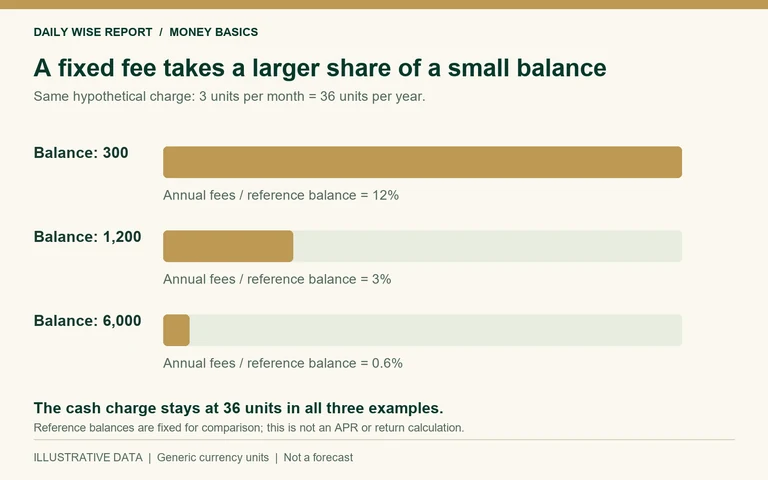 Analysis
Why a Small Fixed Fee Can Be Expensive on a Small Balance
The same charge can have very different effects depending on the balance, transaction size and length of time.
Read full articleFour concepts. Many different outcomes.
These explanations cover general financial concepts. Product terms, tax treatment, and legal protections vary by country.
Interest & Compounding
How balances change over time.
Explore concept ↓02Inflation
Why average prices and personal experience differ.
Explore concept ↓03Purchasing Power
The difference between a number and what it buys.
Explore concept ↓04Cash Flow
Why the timing of money matters.
Explore concept ↓Interest & Compounding
Interest is a charge for borrowing money or an amount earned on an interest-bearing balance. With compounding, interest is calculated on a balance that includes previously accumulated interest.
How the mechanism works
In a hypothetical example, 1,000 currency units earning a fixed 5% annually become 1,050 after one year and 1,102.50 after two, assuming annual compounding, no withdrawals, fees, or taxes. This is arithmetic, not a forecast.
Negative effects & limitations
Fees, taxes, and inflation can reduce the value of interest earned. On debt, the effect depends on the contract, payments, and whether unpaid interest is added to the balance.
Inflation
Inflation describes an increase in the general price level over a period. A consumer price index tracks a defined basket; it does not measure every household’s exact spending.
How the mechanism works
If income grows more slowly than the prices of what a household buys, its purchasing power falls. Spending patterns differ, so households can experience different pressures even when the headline inflation rate is the same.
Negative effects & limitations
Negative effects can include pressure on fixed incomes and loss of purchasing power. Effects on borrowers and lenders depend on interest terms, income changes, and whether inflation was anticipated.
Purchasing Power
Purchasing power is the quantity of goods and services money can buy. A larger nominal balance does not necessarily represent greater purchasing power.
How the mechanism works
If a balance rises by 3% while the price of the same basket rises by 5%, its purchasing power changes by 1.03 ÷ 1.05 − 1, or approximately −1.90%. This simplified example assumes one period and excludes fees and taxes.
Negative effects & limitations
A national average can hide differences in housing, food, and energy costs. Comparisons across countries also depend on local prices and exchange rates; converting currencies alone does not establish equal living standards.
Cash Flow
Cash flow describes money received and paid during a period. It differs from wealth: someone can own valuable assets while having little cash available for an immediate bill.
How the mechanism works
Consider a hypothetical month with 2,000 units received and 1,800 paid. The net flow is positive by 200, yet a bill due before income arrives can still create a temporary shortfall.
Negative effects & limitations
Delayed income, irregular expenses, and debt payments can create pressure. One positive month does not establish long-term stability, and an asset sale may improve cash flow while reducing assets.
Sources & scope
Conceptual references: CFPB: Compound interest, CFPB: Financial terms glossary, and IMF: Inflation.
Examples are hypothetical and use generic currency units. References to US educational resources support general definitions, not claims about rules in other countries. Reviewed October 14, 2026.
Mechanisms
Explain how a concept works.
Consequences
Include costs and negative effects where relevant.
Limitations
Identify assumptions and differences in scope.